Afterpay: Pay over time

- 71.00K Reviews
- 4.0
- Downloads
- 10,000,000+
Our take on Afterpay: Pay over time from Appgk
When I want to split the cost of an online purchase, I usually care less about flashy shopping features and more about whether the payment process stays understandable from the first tap to the final instalment. Afterpay: Pay over time is built for that exact moment: I have found something I need, the full price is uncomfortable today, and I want a structured way to spread the payment. After using it as a shopping app rather than treating it as a simple checkout button, I found it most useful when I planned the purchase before browsing too deeply.
Developed by Afterpay, this free shopping app has a mature audience rating of 17+, runs on Android 7.0 or later, and is currently listed as version 1.142.0. Its store summary focuses on flexible payments, but the practical experience is more nuanced. The app can make a planned purchase easier to manage, yet it can also make an unnecessary purchase feel more affordable than it really is. The important question is not only whether I can divide a payment, but whether the complete payment schedule still fits my budget.
From a planned purchase to a completed payment
Starting with the real need
The best starting point is a specific shopping need, not the promise of paying later. I would open Afterpay when I already know what I am looking for, such as replacing an everyday item, preparing for an event, or comparing products from participating retailers. That approach helps me keep the financing tool in its proper place: it supports a purchase decision instead of becoming the reason for one.
The app belongs to the shopping category, so it feels more useful when I treat it as part of the buying journey rather than as a general money-management tool. I still need to decide whether the product is worth its full price, whether delivery and other charges affect the total, and whether the scheduled payments fit alongside rent, food, subscriptions, and existing commitments. The app can organize a payment arrangement, but it cannot make an expensive item inexpensive.
Best Parts of Afterpay: Pay over time
Things to Keep in Mind About Afterpay: Pay over time
For someone new to this type of service, the first practical question is whether Afterpay can be used for the intended retailer and purchase. That is where browsing inside the app can help: it gives me a route toward eligible shopping destinations instead of leaving me to guess at checkout. I would still read the retailer’s product details and the final order summary carefully, because the payment method does not replace the retailer’s own rules about stock, shipping, returns, or exchanges.
Moving from discovery to checkout
Once I have chosen an item, the next stage is the handoff between shopping and payment. This is where the app’s value becomes visible. Rather than paying the entire amount immediately, I can select the Afterpay option when it is available and review the proposed schedule before confirming. I find that preview especially important because it changes the decision from “Can I afford this today?” to “Can I comfortably meet each scheduled payment?” Those are not the same question.
News and Features Related to Afterpay: Pay over time

News
YouTube Turns a Quick Video Check Into an Hour of Watching

News
BeautyPlus Makes Portrait Retouching Feel Like Your Own

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo
A useful habit is to pause at this point and write down the total commitment in my own notes. I include the purchase amount and any extra cost shown during checkout, then compare the timing with my regular income. This small step prevents the app from becoming a collection of separate reminders that look harmless individually but become difficult when several purchases overlap. It is one of the less obvious ways to use a pay-over-time service responsibly: I treat each plan as a real obligation, not as a discount.
The checkout experience also depends on the retailer’s implementation. Some shoppers will reach the payment choice directly from a store’s checkout, while others may begin by exploring offers or retailers through the Afterpay app. That transition can feel smooth when the product, basket, and payment choice remain clear. It can feel less direct when I move between retailer pages and the payment app and have to recheck whether I am still looking at the same item, total, or order.
Don't want to read the full review?
Understanding the payment schedule before agreeing
The schedule is the part I would never rush. I look for the amount due now, the later instalments, and the dates attached to them. I also consider whether my bank balance will be healthy on those dates, not merely on the day I place the order. If a payment is scheduled close to another large bill, the purchase may be a poor fit even if the first payment seems manageable.
This is also where Afterpay differs from an ordinary debit-card purchase. A normal payment is simple to understand: the money leaves once, and the transaction is finished. With this app, the purchase remains active across several payment moments. That can be helpful for cash flow, but it creates an administrative task. I need to monitor the plan, keep the payment method usable, and respond promptly if something changes with the order or my finances.
Screenshots
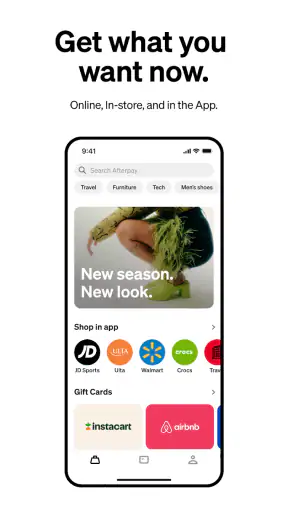
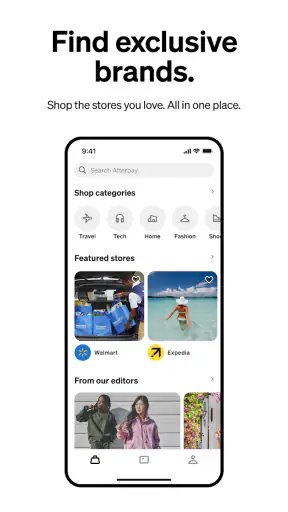
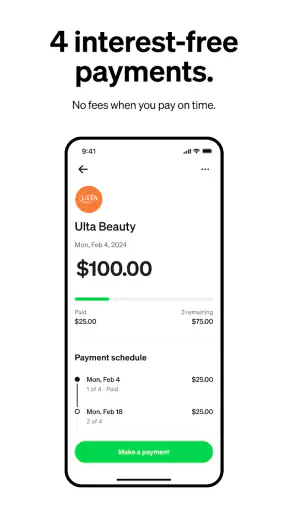
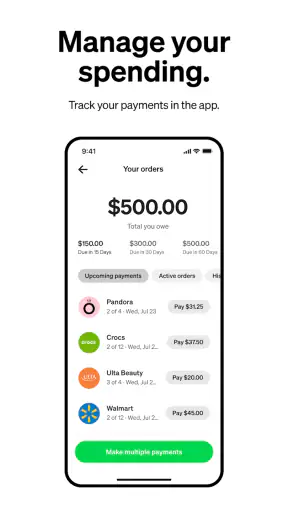
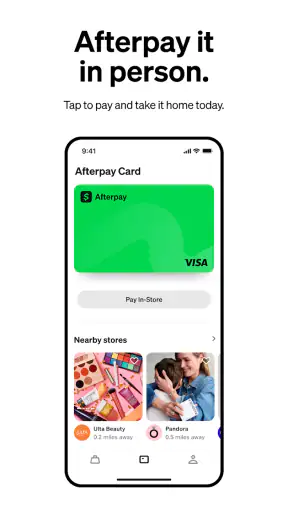
I would not use the app as a substitute for an emergency fund. If I am relying on future income that is uncertain, or if the purchase is not genuinely necessary, the flexibility can work against me. The most suitable user is someone who already has a clear repayment plan and wants timing flexibility. The least suitable user is someone who regularly forgets bills, has several unstable obligations, or is using instalments to buy far beyond a comfortable budget.
The handoff between Afterpay and the retailer
One of the most important details is that the shopping experience has two sides. Afterpay handles the payment arrangement, while the retailer handles the product order. If the item arrives late, is the wrong size, or needs to be returned, I may need to deal with the retailer first. The app can show the payment side of the purchase, but it does not remove the need to keep order confirmations, shipping details, and return instructions.
That division of responsibility is easy to overlook when the checkout feels like one continuous process. My practical advice is to save the retailer’s order information immediately and keep it separate from the payment schedule. If I return something, I want to know exactly which order is affected and whether the payment plan has been updated. I would not assume that sending an item back automatically explains every payment detail inside the app.
The same principle applies to cancellations and partial changes. A retailer may have its own process for adjusting an order, while the payment arrangement may take time to reflect the outcome. I find it safer to check both sides: the retailer’s confirmation and the Afterpay plan. This two-record habit is more work than paying by card once, but it prevents confusion when an order changes after checkout.
Using the app after the purchase
After the order is placed, the app becomes less about browsing and more about follow-through. I use it as a place to review active purchases and remember what is still scheduled. That is a different mindset from opening a shopping app to find something new. The useful outcome is not simply completing an order; it is completing the order without losing track of the remaining commitment.
A realistic example would be buying a replacement appliance accessory before a busy week. I might choose the item, confirm the payment arrangement, and then check the later dates against my pay cycle. If the first payment fits but a later one lands during a period of other expenses, I would either postpone the purchase or pay in full through a usual method. Afterpay helps me see a structured alternative, but the final decision still belongs to my broader budget.
For recurring shoppers, the main risk is accumulation. One plan may be easy to remember, while several plans from different retailers can create a crowded schedule. I would review the app before starting another purchase and count existing commitments, rather than judging each new item on its own. This is a concrete advantage of using the app deliberately: it can expose the combined effect of separate shopping decisions, provided I actually check the plans instead of treating checkout as an isolated event.
What the experience feels like in everyday use
The app’s appeal is its straightforward purpose. I do not need a complicated financial dashboard to understand why I opened it: I am shopping, checking a payment option, or reviewing an existing purchase. Its rating of 4.0 from around 170 thousand ratings suggests a broad range of experiences, and the app has passed the threshold of over 10 million installs. I read that reach as evidence that the service is familiar to many shoppers, not as a guarantee that every checkout will feel identical.
The free price also lowers the barrier to trying it, but “free” should not be confused with cost-free shopping. The product price and the responsibility for later payments remain the central issue. I would judge the app by the clarity and discipline it gives me, not by the absence of an upfront app charge. That distinction matters particularly for younger adults who may be tempted to focus on the first payment rather than the total purchase.
The mature age rating is another useful signal about the intended audience. I would not present this as a casual children’s shopping tool. It involves real purchasing decisions and real payment commitments, so it belongs in an adult household budget conversation. Parents or guardians considering it for a teenager should focus on financial understanding and supervision rather than simply installing the app because the initial payment appears smaller.
Where it is stronger than the usual alternatives
Compared with paying by debit card, Afterpay can be more comfortable when I have the money coming in predictably but want to preserve cash for several scheduled expenses. The advantage is not that the purchase costs less; it is that the timing is divided into visible steps. For a planned item, that can make a difference between a manageable month and an unnecessarily tight one.
Compared with a traditional credit card, the app can feel more focused because the purchase is attached to a specific repayment schedule rather than disappearing into a revolving balance. I personally find that useful for one-off purchases where I want a clear endpoint. A credit card may still be better for someone who values broader acceptance, established rewards, or a single consolidated statement, depending on their existing arrangement and ability to manage it.
Compared with saving first, Afterpay is less financially conservative. Saving avoids creating a future payment obligation, while this app allows the purchase to happen sooner. I would choose saving when the item is optional, the future budget is uncertain, or waiting would not cause a real problem. I would consider Afterpay only when the purchase is justified and the schedule is comfortably covered.
Compared with retailer-specific finance options, the attraction is the shopping-oriented flow and the ability to encounter the service across participating stores rather than tying myself to one retailer. The trade-off is that I still have to understand each retailer’s order and return process separately. For a large purchase where terms, protection, or long-term financing details matter, I would compare the full conditions carefully instead of assuming a familiar checkout button is automatically the best option.
Where the workflow breaks down
The smoothest path is not guaranteed. A purchase can become confusing when the retailer’s basket changes, when shipping or availability alters the final amount, or when I need to return part of an order. The friction is not necessarily a flaw in one screen; it comes from the handoff between two systems with different responsibilities. That is why I would keep both the retailer receipt and the payment-plan information until the order is completely settled.
Another weak point is temptation. Shopping first and thinking about the repayment schedule later encourages me to judge affordability by the initial instalment. I avoid that by checking the complete plan before becoming emotionally attached to the item. If the schedule is difficult to explain in one sentence, or if I need to rely on a future windfall, I take that as a signal to stop.
There is also a practical maintenance burden. I need to keep an eye on scheduled payments, remember overlapping purchases, and act when an order changes. Someone looking for a completely hands-off payment method may prefer a normal card transaction or saving until the full amount is available. The app is most useful for a person willing to manage the arrangement actively.
Device compatibility is reasonably broad because the current app supports Android 7.0 and newer, but compatibility alone does not solve account or checkout difficulties. If the app does not behave as expected during a purchase, I would avoid repeatedly confirming actions without checking the order status. I would first verify whether the retailer received the order and whether the payment plan appears correctly, then contact the relevant side of the transaction rather than assuming one support route handles everything.
Small habits that make the service easier to control
My first habit is to compare the full total with the instalment schedule before I browse for alternatives. This prevents me from choosing an item merely because its first payment looks attractive. My second is to avoid opening a new plan while another order is being returned or changed. Until the first transaction is clear, adding another one makes the account harder to read.
My third habit is to use a simple calendar reminder alongside the app. I do not rely on memory, especially when several purchases are active. A calendar view helps me spot a crowded week before it becomes a problem. This is not a special feature claim about Afterpay; it is a workflow improvement that makes the app’s payment structure easier to manage in real life.
I also separate “available to buy” from “wise to buy.” The app may make a product easy to reach, but I still ask whether I would purchase it if the entire price were displayed in one line. If the answer is no, splitting the payment is probably hiding the real decision rather than solving it.
Who should use it, and who should choose something else
I would recommend Afterpay to a careful shopper who has predictable income, understands the total commitment, and wants a clear way to divide a planned purchase. It is particularly practical when the item is needed soon and paying the entire amount immediately would disrupt an otherwise healthy monthly budget. The app’s shopping focus also makes sense for people who prefer discovering eligible retailers and handling the payment choice within one familiar service.
I would tell a friend to skip it if they are already behind on bills, frequently forget payment dates, or are using instalments to justify impulse purchases. I would also choose another route for a purchase that requires unusually strong long-term financing, detailed credit comparison, or a simple one-time payment with no future administration. In those situations, saving first, paying by debit card, or comparing a different financial product may be clearer.
Afterpay: Pay over time is a useful tool when I begin with a sound purchase decision and use the app to organize timing. It is less useful when the payment schedule becomes a psychological trick that makes an unaffordable item appear harmless. I like the convenience, the focused shopping flow, and the ability to review a purchase beyond the initial checkout, but I would keep the retailer handoff and overlapping plans firmly in mind. My final recommendation is simple: use it for planned purchases, inspect every scheduled payment, keep the order records, and never let a smaller first payment replace a realistic view of the full cost.
Afterpay: Pay over time FAQ
What is Afterpay: Pay over time, and how does it work?
Afterpay is a buy now, pay later service that lets you split eligible purchases into several scheduled installments, usually without interest when payments are made on time. After downloading the app, you can browse participating retailers, create a virtual shopping experience, review available payment plans, and manage upcoming installments from one place. Approval is not guaranteed for every purchase or user.
Does Afterpay charge interest or additional fees?
Afterpay generally promotes interest-free installment payments when you follow the agreed payment schedule, but that does not mean every use is completely free of charges. Late fees, account-related costs, or other restrictions may apply depending on your location, plan, and retailer. Before confirming an order, carefully review the total amount, payment dates, possible fees, and the current terms shown in the app.
What do I need to use Afterpay on Android or iPhone?
To use Afterpay, you typically need a compatible Android or iOS device, an internet connection, a supported payment method, and an account containing accurate personal information. Eligibility requirements can vary by country and may include age, residency, identity, and credit or risk checks. The app may also require permissions for notifications or shopping features, although you should review permissions before accepting them.
Can I use Afterpay at any store, and can I shop in-store?
Afterpay is not accepted at every retailer. The app includes a directory or shopping tools that help identify participating stores and available products, while some merchants may support online checkout, in-store payments, or both. Availability can depend on your region, account status, purchase amount, and retailer rules. Always confirm that the payment option is available before spending time preparing an order.
What happens if I miss an Afterpay payment or need a refund?
If you miss a scheduled payment, Afterpay may restrict further purchases, charge a late fee where permitted, and continue attempting to collect the outstanding amount according to its terms. If you return an item, the retailer normally must process the refund first, after which Afterpay updates the installment schedule. Until the refund is confirmed, you may still be responsible for payments, so keep receipts and monitor the app.